

Ditch: Pay Off Debt Faster
Ditch Technologies, Inc
- 4.8
- 59.00 Reviews
- 10.00K
- Downloads
- Free
- Price
Screenshots
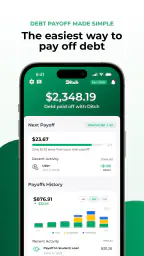
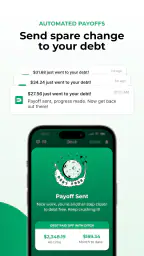
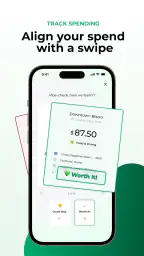
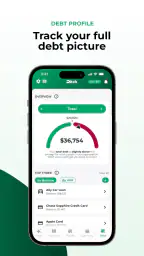
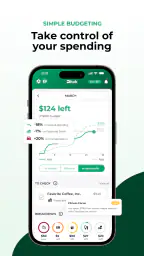
Ditch: Pay Off Debt Faster Pros and Cons
Pros
- Clear payoff tracking helps visualize progress toward becoming debt-free.
- Supports extra-payment planning to estimate how quickly debt can be reduced.
- Simple interface makes it easy to review balances and repayment goals.
- Useful reminders can help users stay consistent with scheduled payments.
- May encourage better financial habits through visible milestones and progress.
Cons
- Requires accurate debt details to produce useful repayment estimates.
- Limited value for users who already manage debt with a detailed budget.
- Does not eliminate interest charges or negotiate with creditors.
- Some features may require a subscription or in-app purchase.
- Financial results depend on maintaining payments and following the plan.
 Analysis by All-app
Debt payoff usually fails for a surprisingly ordinary reason: the plan is too difficult to keep visible. I have found that people often know what they owe, yet still struggle to turn several balances, due dates, and minimum payments into one routine they can follow. Ditch: Pay Off Debt Faster takes a focused approach to that problem by putting payoff planning and debt tracking at the center of a finance app rather than burying them among broader budgeting tools.
After using it, my impression is that Ditch is most useful when you want a clear view of progress and a more deliberate way to direct payments. It is not trying to be a complete replacement for your bank, and I would not treat it as a magic shortcut that removes the need for discipline. Its value is more practical: it gives debt a defined place in your financial routine, so the next decision is easier to make.
The app comes from Ditch Technologies, Inc and is available free of charge for Everyone. It has a 4.8 average from around one thousand ratings, with more than ten thousand installs, which suggests that its narrow purpose is connecting with people who want help getting out of debt. The Android release requires version 8.0 or later, and the current version is 1.5.5. Optional in-app purchases range from $5.99 to $89.99 per item, so I would pay attention to any upgrade screen before committing to paid tools.
Turning a debt list into a payoff plan
I find that the most useful way to approach this section is to treat a payoff plan as something to check at decision points, not as a promise that runs unattended. I’ll look at how Ditch can help turn a scattered set of balances into a routine, while keeping lender records and day-to-day affordability in view. That distinction matters especially when the plan needs to adapt to real life.
The central capability is direction, not just record keeping
The strongest idea behind Ditch is the connection between tracking debt and planning how to pay it off. A simple list of balances can tell you what exists, but it does not necessarily tell you what to do next. A useful payoff tool needs to make the difference between “I have debt” and “this is the next payment decision” easier to see.
That distinction matters when you have more than one obligation. A credit card, personal loan, and medical balance may all have different amounts and payment expectations. Looking at them separately can make the situation feel scattered. A dedicated payoff view gives you a reason to review them together and judge progress as one longer project.
In my experience, the psychological benefit is just as important as the arithmetic. Debt reduction can feel slow when every payment disappears into a large balance. Tracking creates smaller checkpoints: the account was added, a payment was made, the remaining amount changed, and the overall plan moved forward. Those details do not lower the debt by themselves, but they make it harder to lose sight of the work.
More Reads From Our News Desk

Switching to the Xbox App: What Changes in Your Gaming Routine

Coloring & Learn Review: A Satisfying Canvas, Cluttered Menus

Microsoft 365 Copilot on Your Phone: Who Actually Needs It?

Mafia City: The Crime Saga That Outshines Its Rivals

Woodturning Transformed: How OS Updates Enhance Your Craft

How Tiles Hop EDM Rush Redefines Music Gaming
I also like that the app’s purpose is immediately understandable. The store summary, “Automate Payoff & Track Debt,” points to a specific job rather than promising to manage every part of personal finance. That narrow focus can be an advantage for someone who opens a general budgeting app and becomes distracted by categories, spending charts, or unrelated financial tools.
What I would use it for first
My first step would be to gather the information needed for a realistic debt picture before trying to optimize anything. I would have the latest statements nearby and enter each obligation carefully, checking the balance and required payment against the source. This is one of the most important practical habits with any debt tracker: an attractive plan built on outdated numbers can create false confidence.
Once the accounts are represented, I would use Ditch as a weekly or payday checkpoint. The purpose is not to stare at the app every day. It is to open it when money is about to be assigned, confirm what has changed, and decide whether the planned payment still fits the month. That workflow keeps the app connected to a real financial moment instead of turning it into another dashboard that you rarely revisit.
A useful trick is to separate “what I must pay” from “what I hope to pay.” Minimum obligations protect the account from falling further behind, while extra payments depend on the money left after essentials. Keeping that distinction clear helps prevent an ambitious payoff target from forcing you to rely on a credit card again. Ditch can support the planning conversation, but I still need to make the final judgment using my actual cash flow.
Automation needs sensible boundaries
The word “automate” deserves careful interpretation. I would not assume that a debt planning app can safely make every payment decision without oversight. Automatic tracking or a guided payoff routine can reduce mental effort, but account balances, interest, fees, and due dates can change. I would still review the plan before each meaningful payment, especially after a new purchase, a returned payment, or a change in income.
This is where Ditch is best viewed as a decision aid rather than a substitute for a lender’s account portal. The lender remains the authoritative place for payment status and posted amounts. The app is more useful for organizing the bigger picture and keeping the payoff objective visible. That division of responsibility is a strength, provided you do not mistake convenience for complete financial automation.
A realistic payday routine
Imagine that I am paid on Friday and have three debts competing for attention. Instead of sending extra money impulsively to whichever balance looks most annoying, I would open Ditch, review the plan, and compare the proposed payment with rent, food, transport, and upcoming bills. I would then check the lender accounts separately before sending anything.
If the month is tighter than expected, the app still has a role. I can preserve the required payments, reduce the extra amount, and keep the plan honest rather than abandoning it because the original target was too aggressive. If the month is better, I can decide whether the extra money should go toward the selected payoff target or remain available for an emergency. The important improvement is the pause between receiving money and assigning it.
That pause is a non-obvious benefit of a focused debt app. It can interrupt the common habit of making emotional payments without checking the rest of the month. Paying debt faster is valuable, but paying so much that you need to borrow again is not progress. A plan should be judged by whether it survives ordinary life, not just by how quickly it looks on paper.
Where Ditch fits, and where it does not
Here I’ll place Ditch alongside the tools people already use, from bank apps to spreadsheets and broader budgeting services. Its debt-focused approach can make the next step easier to see, but it is not automatically the right fit for every financial situation; the following comparison helps clarify when that focus is useful and when I’d choose something else.
The best scenario is a manageable set of debts
I think Ditch makes the most sense for someone who has several debts, a reasonably stable income, and a genuine desire to follow one payoff path. That person may not need a full household accounting system. They need a place to keep the debt project organized and a reason to review it consistently.
It is also a good fit for someone who has tried to track balances in notes, spreadsheets, or scattered banking screens and keeps losing the thread. A spreadsheet can be more flexible, but flexibility creates work: formulas need maintenance, dates need updating, and the person must design the payoff logic. Ditch’s appeal is that it starts from the debt problem itself.
Another strong use case is a couple or household where one person handles most payments but both people need a shared understanding of progress. Even if the app is not used as a complete joint financial system, a dedicated payoff view can provide a common reference for conversations about extra payments and timing. I would still agree on who updates the figures, because duplicated or inconsistent entries can undermine trust in any tracker.
Compared with banking apps and spreadsheets
Your bank’s app is usually better for checking the live status of an account, confirming a payment, and viewing transactions. It is not always designed to show several debts as one long-term project. Ditch fills that planning gap. I would use the bank app for verification and Ditch for the broader payoff perspective.
A spreadsheet remains the better choice for someone who wants complete control over formulas, custom categories, irregular income, or a detailed household budget. It can also be easier to archive and inspect manually. The trade-off is that building and maintaining it takes more effort, and a spreadsheet does not automatically become motivating simply because it is precise.
A general budgeting app may be preferable when debt is only one part of a larger money problem. If overspending, irregular bills, savings, and cash-flow forecasting are the main challenges, a broader tool may give you a more complete answer. Ditch is more compelling when the question is narrower: how do I keep my debt payoff organized and moving?
The main trade-off is focus
Focus is both the app’s advantage and its limitation. A debt-centered experience can feel refreshingly direct, but it may not replace the surrounding habits needed to stay solvent. You still need to watch spending, protect an emergency cushion, and understand the terms of each debt. If you only track balances without examining why new debt appears, the app may show the problem clearly without solving its cause.
I would also avoid entering figures casually. A balance copied from memory, a missed fee, or an incorrect required payment can distort the plan. My practical advice is to update after statements close or after an important payment posts, rather than changing numbers whenever I happen to remember them. That creates a cleaner history and makes progress easier to interpret.
The optional purchase range is another consideration. The app itself is free, but some items cost between $5.99 and $89.99. I would begin with the free experience and decide whether any paid capability addresses a specific problem I actually have. A debt tool should save effort, not encourage spending simply because a premium screen makes the plan look more polished.
Who should skip it
I would skip Ditch if you want a full banking replacement, automatic control over every financial account, or a detailed budget covering investments, subscriptions, and household spending. Its debt-first purpose is not a weakness for the right user, but it is a mismatch for someone seeking an all-in-one financial command center.
I would also be cautious if your income changes dramatically from week to week and your payoff plan needs constant forecasting. A focused tracker may still help, but you will need to do more manual judgment around each payment. In that situation, a flexible spreadsheet or cash-flow budgeting system could be a better primary tool, with Ditch used only if its payoff view adds clarity.
Finally, anyone facing serious payment trouble should not rely on an app alone. A tracker can organize information, but it cannot negotiate with creditors or replace qualified financial guidance. If minimum payments are already unaffordable, the priority is understanding available assistance and avoiding decisions based solely on an optimistic payoff schedule.
Who gains the most from the focused design
The biggest benefit goes to people who are motivated but inconsistent. They do not necessarily need more financial theory; they need a repeatable place to look before making a payment. Ditch gives the debt goal a dedicated home and can turn a vague intention into a sequence of reviews.
It is particularly helpful when progress feels invisible. Seeing one balance decline may be encouraging, but seeing the whole payoff effort organized can make the task feel less chaotic. I would use that visibility to celebrate consistency, not to pressure myself into unsafe payments. A sustainable plan that survives an expensive month is more useful than a perfect plan that collapses immediately.
New users should also decide their review rhythm in advance. A weekly check can work for someone paid weekly, while a payday review may be enough for someone with a regular monthly salary. The key is to connect the app to a real event. Opening it without a decision to make can become a habit with no result; opening it before money is allocated gives the tracking a clear purpose.
My final view after using it
Ditch: Pay Off Debt Faster is a focused finance app with a sensible central promise: make debt payoff easier to organize and harder to ignore. I appreciate that it addresses a specific weakness in ordinary banking apps, which often show balances without helping me maintain a long-term payoff routine.
My recommendation comes with a boundary. Use it as the planning layer, verify payments with the lenders, and keep the payoff amount realistic alongside everyday expenses. Do not assume automation removes the need for review, and do not buy optional features until you know exactly what problem they solve.
For someone with multiple debts who wants a dedicated, less complicated way to track progress, Ditch is worth trying because its narrow purpose is its clearest strength. For someone needing complete budgeting, detailed cash-flow forecasting, or direct financial assistance, another tool will likely be a better foundation. The app works best when it turns a payoff intention into a small routine you can repeat without putting the rest of your finances at risk.
Frequently Asked Questions
What is Ditch: Pay Off Debt Faster, and how does it help with debt repayment?
Ditch: Pay Off Debt Faster is a personal finance app designed to help you organize debts, understand repayment progress, and build a clearer plan for becoming debt-free. After entering information such as balances, interest rates, minimum payments, and due dates, the app can help you compare repayment approaches and see how additional payments may affect your timeline. It is best used as a planning and tracking tool rather than a substitute for professional financial advice.
Can Ditch manage different types of debt, such as credit cards, loans, and student debt?
The app is intended for users handling multiple debt accounts, including common obligations such as credit cards, personal loans, and other installment balances. You generally need to enter or review each account’s details so the repayment calculations are meaningful. Features and supported debt categories may vary by platform or subscription level, so it is worth checking the current app listing before downloading if you have unusual loans, variable interest rates, or complicated repayment arrangements.
Does Ditch connect directly to my bank accounts or require manual information?
Depending on the version and region, Ditch may offer ways to enter debt information manually and may provide integrations or account-connection features. Users should carefully review what access is requested before linking any financial account. Manual entry can take longer, but it gives you more control over the information stored in the app. Always verify balances, interest rates, and payment dates yourself because automatically imported financial data can occasionally be delayed or inaccurate.
Is Ditch free to download, and are there subscriptions or in-app purchases?
Ditch may be available to download without an upfront charge, but some planning tools, advanced calculations, tracking features, or other functionality can require a subscription or in-app purchase. Pricing, trial periods, and renewal terms may differ between Android and iOS and can change over time. Before starting a trial, review the payment screen carefully, including the renewal price and cancellation instructions, so you understand the ongoing cost.
Is Ditch safe to use for sensitive financial and debt information?
Because a debt-planning app may contain highly sensitive information, users should review its privacy policy, data practices, permissions, and security details before entering personal or account information. Use a strong device passcode and avoid sharing login credentials. If the app supports bank connections, confirm whether a reputable secure provider handles authentication. Ditch can support financial organization, but it should not be treated as a bank, lender, credit counselor, or guarantee of debt reduction.


